IBAN4U alternative for iGaming, crypto and PSP businesses
IBAN4U is the account brand of FinXP, a Malta e-money institution that repositioned as payments infrastructure in September 2026. Narvi is a Finnish e-money institution with dedicated offers for iGaming and crypto businesses. Here's how they compare.

The short answer. Choose Narvi if you want pricing you can see before you pay anything, a 10-minute online application, and an iGaming offer that's still a named product. Consider FinXP's IBAN4U if you need card issuing or BIN sponsorship, FX payouts to more than 60 currencies, or a payment gateway alongside your account.IBAN4U is the account brand of FinXP Limited, a Malta e-money institution formerly called Paymentworld Europe Ltd. In September 2026 FinXP relaunched its website and repositioned itself as payments infrastructure [18]. Every FinXP fact below comes from FinXP's own pages and help centre as of 21 October 2026, linked at the end.
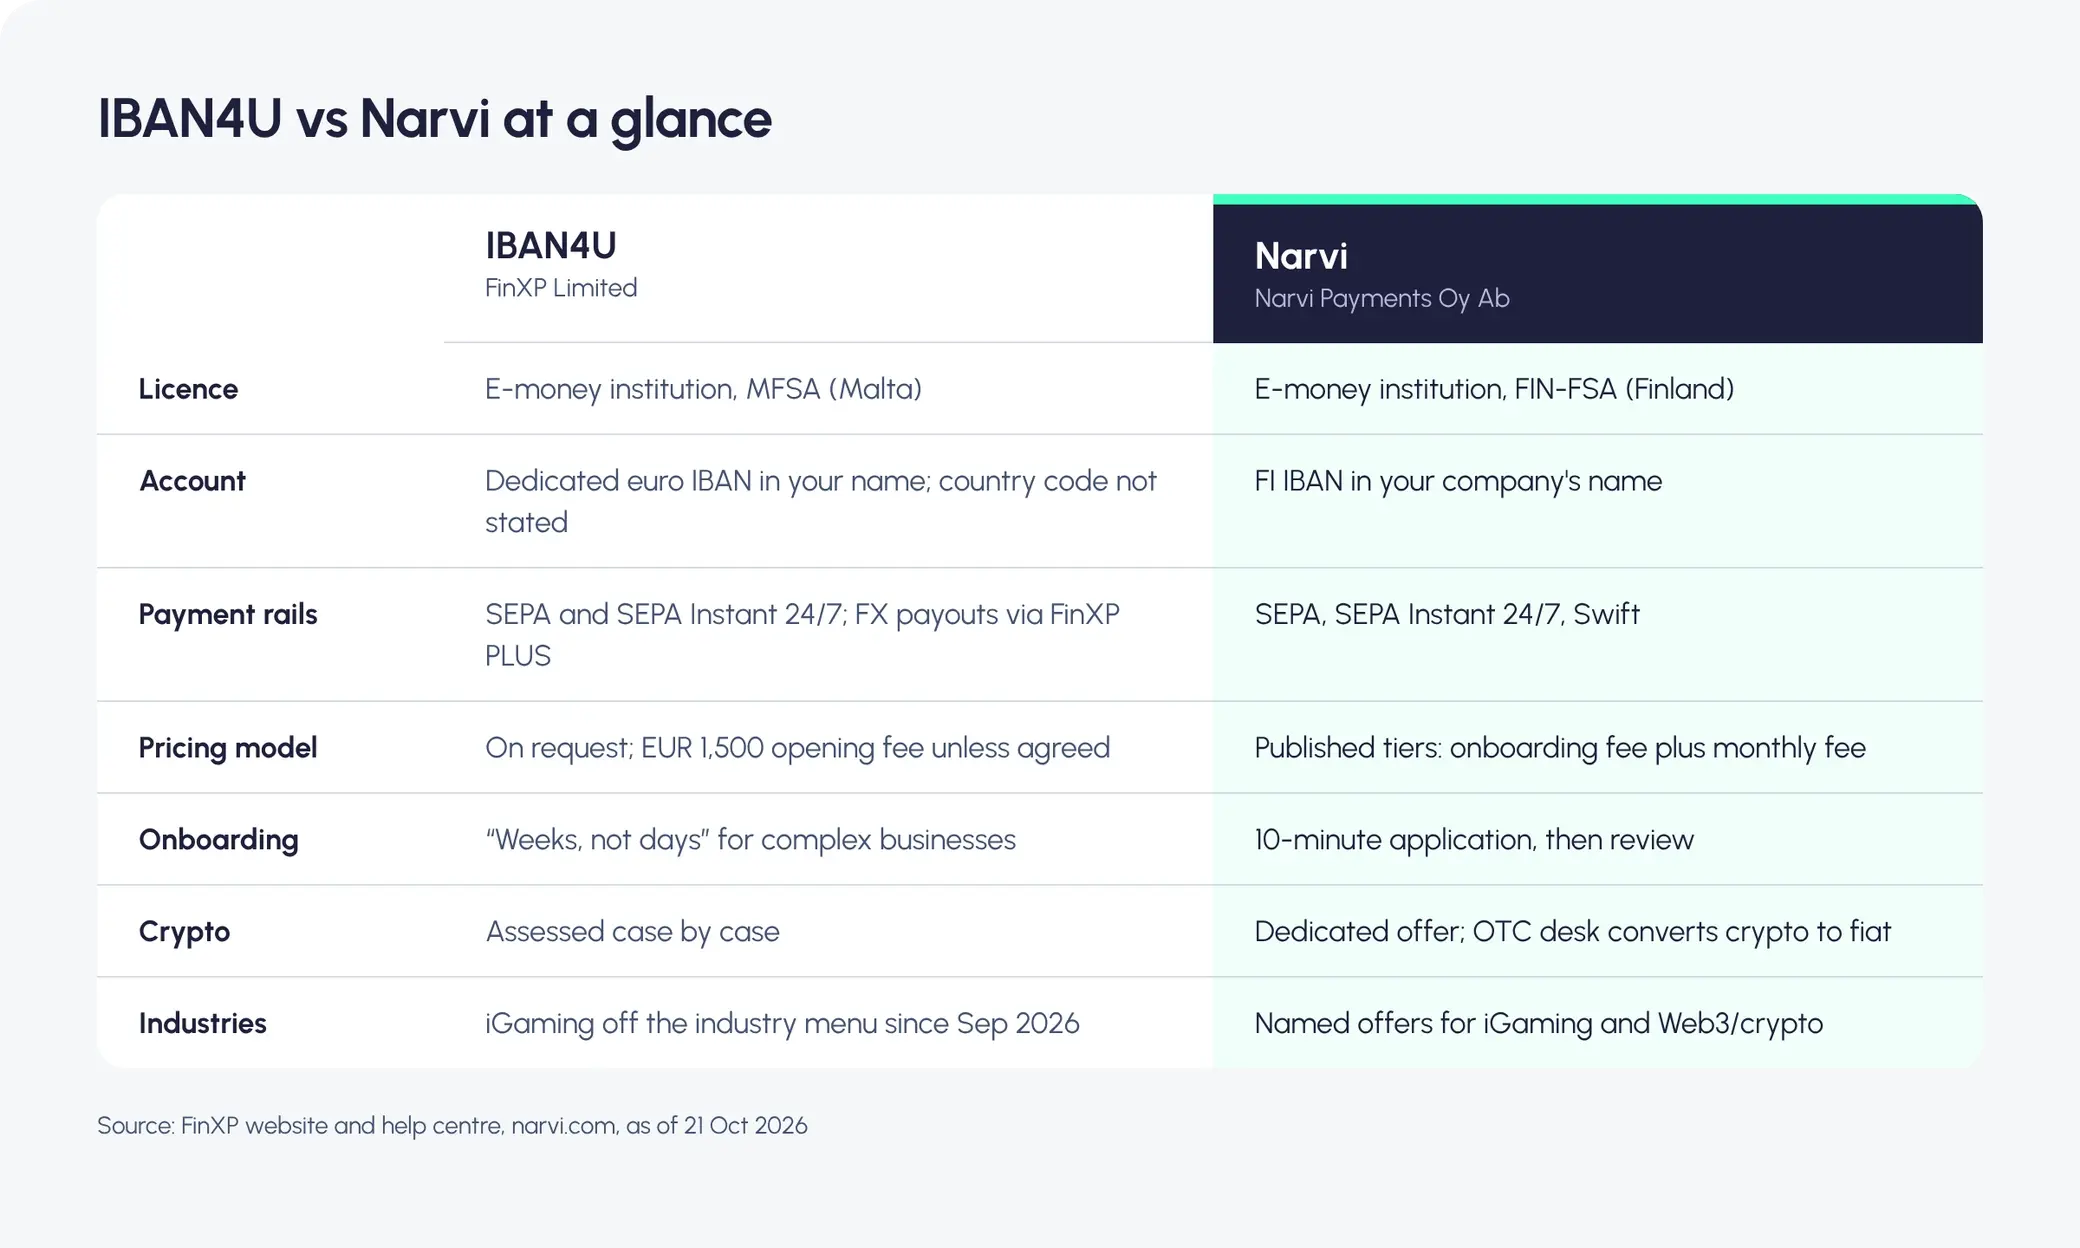

At a glance
IBAN4U vs Narvi at a glance
Every FinXP fact below is as stated on FinXP's website and help centre on 21 October 2026. Each number in brackets links to its source; the full list is at the end of the page.Licence- FinXP Limited (IBAN4U is its account brand): e-money institution under Malta's Financial Institutions Act, supervised by the Malta Financial Services Authority; company registration C 65783 [1][2][3]
- Narvi (Narvi Payments Oy Ab): e-money institution, Finnish Financial Supervisory Authority (FIN-FSA), registration 3190214-6, passported across the EEA [19]
- FinXP: sales-led direct accounts plus Banking-as-a-Service, BIN sponsorship and closed-loop card programmes; non-EU companies accepted [4][5]
- Narvi: businesses, personal accounts for business owners, Banking-as-a-Service and white label [20][26]
- FinXP: its site navigation names fintechs, PSPs and banks; digital assets and Web3; marketplaces and platforms; payroll and contractors; and digital commerce. iGaming and FX and brokerage still appear on the application form and About Us page. No prohibited list is published; crypto is assessed case by case [6][7][8][11]
- Narvi: dedicated offers for iGaming and Web3/crypto businesses; crypto exchanges, payment services and high-risk industries go on a custom enterprise plan [20][21][22]
- FinXP: dedicated euro IBAN in the company's name, which FinXP describes as "not a pooled or virtual" account. The IBAN country code isn't stated [1][12]
- Narvi: dedicated IBAN in your company's name, starting with FI, under Narvi's own BIC [23]
- FinXP: SEPA and SEPA Instant, send and receive, 24/7, with Verification of Payee; no Instant limit published [13]
- Narvi: SEPA and SEPA Instant 24/7, Instant at the SEPA price up to EUR 100,000 per payment; Swift payments via pooled accounts [24]
- FinXP: on request, by industry and volume. Account opening fee EUR 1,500 unless agreed otherwise, charged on approval; the tariff is sent after the account opens [14][15]
- Narvi: one-time onboarding fee plus three months of monthly fees up front; monthly fee by risk tier; minimum balance of three monthly fees (see pricing) [20]
- FinXP: enquiry form, background checks, then a full application with human review; for complex businesses, "weeks, not days". Documents include a signed structure chart, a third-party questionnaire and a board resolution [7][16]
- Narvi: 10-minute online application, then a compliance review and a priced offer [20]
- FinXP: crypto businesses assessed case by case; no crypto services in the account [11]
- Narvi: IBANs hold fiat only [25]
- FinXP: Mastercard principal member card issuing and BIN sponsorship, API-first Banking-as-a-Service and white label, payment gateway, SEPA Direct Debit, mass payouts, sub-accounts [17][4]
- Narvi: business API with public documentation; Banking-as-a-Service, white label and roles for users such as directors, accountants and employees, with API access [26][27]
Pricing
Know the price before you pay anything
FinXP prices IBAN4U accounts on request, by industry and volume. The account opening fee is EUR 1,500 unless agreed otherwise, charged when your application is approved, and the full tariff is sent after the account opens [14][15].Narvi publishes its pricing structure and tiers: a one-time onboarding fee, a monthly fee set by risk tier, and three months paid up front [20]. Crypto exchanges, payment services and other high-risk businesses are priced after compliance review. Either way, you get the priced offer before you fund the account.Onboarding
Onboarding: a 10-minute application, then review
FinXP starts with an enquiry form and background checks, then a full application reviewed by its team. It says complex businesses should expect "weeks, not days", and asks for documents such as a signed group structure chart, a third-party questionnaire and a board resolution [7][16].Narvi's online application takes about 10 minutes, followed by a compliance review and a priced offer [20]. How long the review takes depends on your structure and industry, and the document list is published, so you can prepare before you start.An undated FinXP help-centre article mentions a general minimum of EUR 1 million in annual revenue [5]. It isn't on the new site, so ask whether it still applies. Narvi doesn't publish a revenue minimum; your tier depends on risk.Compliance
Working with the compliance team
Both providers are obliged entities under EU anti-money laundering rules, so AML and KYC checks apply to every client. Both onboard through a human review by a compliance team, not an automated yes or no. FinXP's team reviews a full application after its initial background checks [7].At Narvi, the compliance team reviews your documents before you get a priced offer [20], so you know your tier and fees before you fund the account.If you run iGaming, crypto or payment services, expect detailed questions about source of funds, your ultimate beneficial owners, your licences, where your customers are, and how money moves through your business. Having this ready is the fastest way through review at either provider.Compliance doesn't stop once the account opens. Every EMI runs ongoing transaction monitoring, so tell your compliance contact before you add a new market, a new PSP or a large jump in volume, not after. Ask each provider how they handle these changes before you sign.Safeguarding
How client funds are safeguarded: e-money institutions vs payment institutions
FinXP and Narvi are both regulated e-money institutions, so the same EU framework of safeguarding protections applies to client funds at each. The E-Money Directive requires an EMI to protect the money it receives for e-money in the way the Payment Services Directive sets out for payment institutions [28][29]:- Segregation: client funds are kept apart from the institution's own money and shielded from its other creditors if it becomes insolvent, either in a separate account at a credit institution or in secure, liquid, low-risk assets.
- Insurance or guarantee: an insurance policy or a guarantee from an insurer or credit institution covers the same amount instead.
Payments
SEPA payments and receiving payments in multiple currencies
For European payments in euros the two are close. SEPA covers 41 countries and territories under one payment framework, and SEPA Instant, the instant version of the SEPA Credit Transfer scheme, makes funds available within 10 seconds, 24/7. Both send and receive SEPA payments and SEPA Instant 24/7 from a dedicated IBAN in your company's name [13][24]. Narvi sends SEPA Instant at the SEPA price up to EUR 100,000 per payment; FinXP doesn't publish an Instant limit. Under the EU Instant Payments Regulation, euro-area providers can't charge more for SEPA Instant than for a standard SEPA transfer, so time-sensitive payments no longer cost extra.Outside the euro the gap is wider. FinXP pays out in more than 60 currencies to more than 130 countries through FinXP PLUS, and says it processes more than EUR 4 billion a year across 12,000+ business accounts [12][1].Narvi balances are held in euros, and Swift payments currently run through pooled accounts [25].If most of your revenue arrives in euros and you want SEPA payments and Swift in one account, Narvi covers it. If you need automated payouts in multiple currencies with global reach, FinXP's capabilities cover more today.Whichever you choose, ask what FX margin applies when a payer sends you a non-euro payment.iGaming
iGaming as a named offer
Since its relaunch on 3 September 2026, FinXP's industry navigation no longer includes iGaming [18][6]. iGaming hasn't disappeared: it's still on the application form and the About Us page, and FinXP is exhibiting at SiGMA World in Rome from 2 to 5 November 2026 [7][8][9]. It's de-emphasised rather than dropped.Narvi keeps a dedicated account offer for iGaming operators, platforms and affiliates, and another for crypto businesses [21][22]. Medium and high-risk tiers cover B2B payments only, so if you pay out to players or consumers, you need the enterprise plan, and we'll tell you that before you're priced.When to stay
When IBAN4U is the better choice
FinXP is a Mastercard principal member that issues cards and sponsors BINs for other programmes [17], and pays out in more than 60 currencies through FinXP PLUS [12]. It also offers a payment gateway, SEPA Direct Debit, mass payouts and sub-accounts [4]. If you need card issuing features or wide FX payouts from your account provider, FinXP covers more of that today. Both providers give you a dedicated IBAN in your company's name, so if your IBAN4U account works and the pricing suits you, you don't need to move.How to switch
Switching from IBAN4U to Narvi
What to prepare. You'll need your company documents, details of your directors and owners, and a short description of where your money comes from and goes. The full document list is in our help centre.- Book a short call with the onboarding team for a pricing estimate based on your business profile.
- Complete the online application, which takes about 10 minutes (step-by-step guide).
- Our compliance team reviews your documents and sends a priced offer.
- Fund the account: the onboarding fee, three months of monthly fees and a minimum balance of three monthly fees [20].
- Run both accounts in parallel so your finance team keeps access to both. Move one payment flow at a time (customers, PSPs, payroll, suppliers) and send each counterparty your new IBAN and the BIC NARYFIH2.
- Close the old account only after the last inbound payment has landed, and check your FinXP agreement for notice periods and closing fees first.

FAQ
Frequently asked questions
Yes. IBAN4U is an account brand of FinXP Limited, an e-money institution in Malta formerly called Paymentworld Europe Ltd.
iGaming no longer appears in FinXP's industry navigation since its September 2026 relaunch, but it's still listed on the application form and About Us page. Ask FinXP directly before you apply.
As of 21 October 2026, FinXP's help centre states an account opening fee of EUR 1,500 unless agreed otherwise, charged on approval. Other fees are set by industry and volume and sent after the account opens.
No. Narvi Payments Oy Ab is an e-money institution authorised by the Finnish Financial Supervisory Authority and passported across the EEA. It holds client funds separately from its own money, as EU e-money rules require.
Yes, through safeguarding rather than deposit insurance. EU law requires an e-money institution to keep client funds separate from its own money, in a separate account at a credit institution or in secure low-risk assets, or to cover them with insurance or a guarantee. Deposit guarantee schemes don't cover e-money.
Yes. Narvi has dedicated account offers for both. Crypto exchanges, payment services and other high-risk businesses go on a custom enterprise plan, priced after compliance review.
Narvi charges a one-time onboarding fee and a monthly fee set by your risk tier, with three months of fees paid up front. Enterprise clients are priced after compliance review. The tiers are on the pricing page.

Get a dedicated FI IBAN in your company's nameOpen an account or talk to the onboarding team about your industry and payment flows.
Sources
Sources
Last checked: 29 October 2026 (FinXP facts: 21 October 2026). Also compare Narvi with ConnectPay, Stable.com, payabl., Genome, Paxum, Bilderlings, Neteller or Kontist, or read our comparison of Wise, Revolut and other alternatives.- FinXP euro IBAN account
- GLEIF record for FinXP Limited
- Estonian FSA, providers of cross-border e-money services
- FinXP Banking-as-a-Service
- FinXP help centre: what kind of businesses can open an IBAN4U account
- FinXP industries
- FinXP open account
- FinXP about us
- FinXP blog: where to find FinXP this autumn
- FinXP terms and conditions
- FinXP digital assets and Web3
- FinXP help centre: what is IBAN4U
- FinXP help centre: SEPA Instant
- FinXP help centre: pricing for IBAN4U
- FinXP help centre: application fee
- FinXP help centre: documents required
- FinXP card issuing
- FinXP: new website and refreshed positioning, 3 September 2026
- FIN-FSA register of supervised entities
- Narvi pricing
- Narvi for iGaming
- Narvi for Web3 and crypto
- Narvi dedicated IBAN
- Narvi SEPA Instant
- Narvi FAQ
- Narvi Banking-as-a-Service
- Narvi multi-user access
- Directive 2009/110/EC (E-Money Directive), Articles 6 and 7
- Directive (EU) 2015/2366 (PSD2), Article 10

Ratkaisut
IBAN-tilit yrityksellesi
Aloita täältä
Ajankohtaista (EN)
Family Offices [whitepaper]Shipping Industry [whitepaper]How to Open a Business Account in FinlandNarvi vs. Wise, Revolut, N26, and other alternativesNarvi vs. Stable.comNarvi vs. payabl.Narvi vs. ConnectPayNarvi vs. IBAN4UNarvi vs. GenomeNarvi vs. PaxumNarvi vs. BilderlingsNarvi vs. NetellerNarvi vs. KontistBlogiPayments Glossary


Narvi Payments Oy Ab on valtuutettu sähköisen rahan laitos (EMI). Narvin EMI-toimiluvan myöntää Finanssivalvonta, jonka rekisterinumero on 3190214-6. Narvin toimilupa on voimassa kaikissa Euroopan unionin maissa.
 Rakennettu ja säännelty Suomessa
© 2026 Narvi. All Rights Reserved.
v1.332.0